








 0 comments
Key Takeaways:
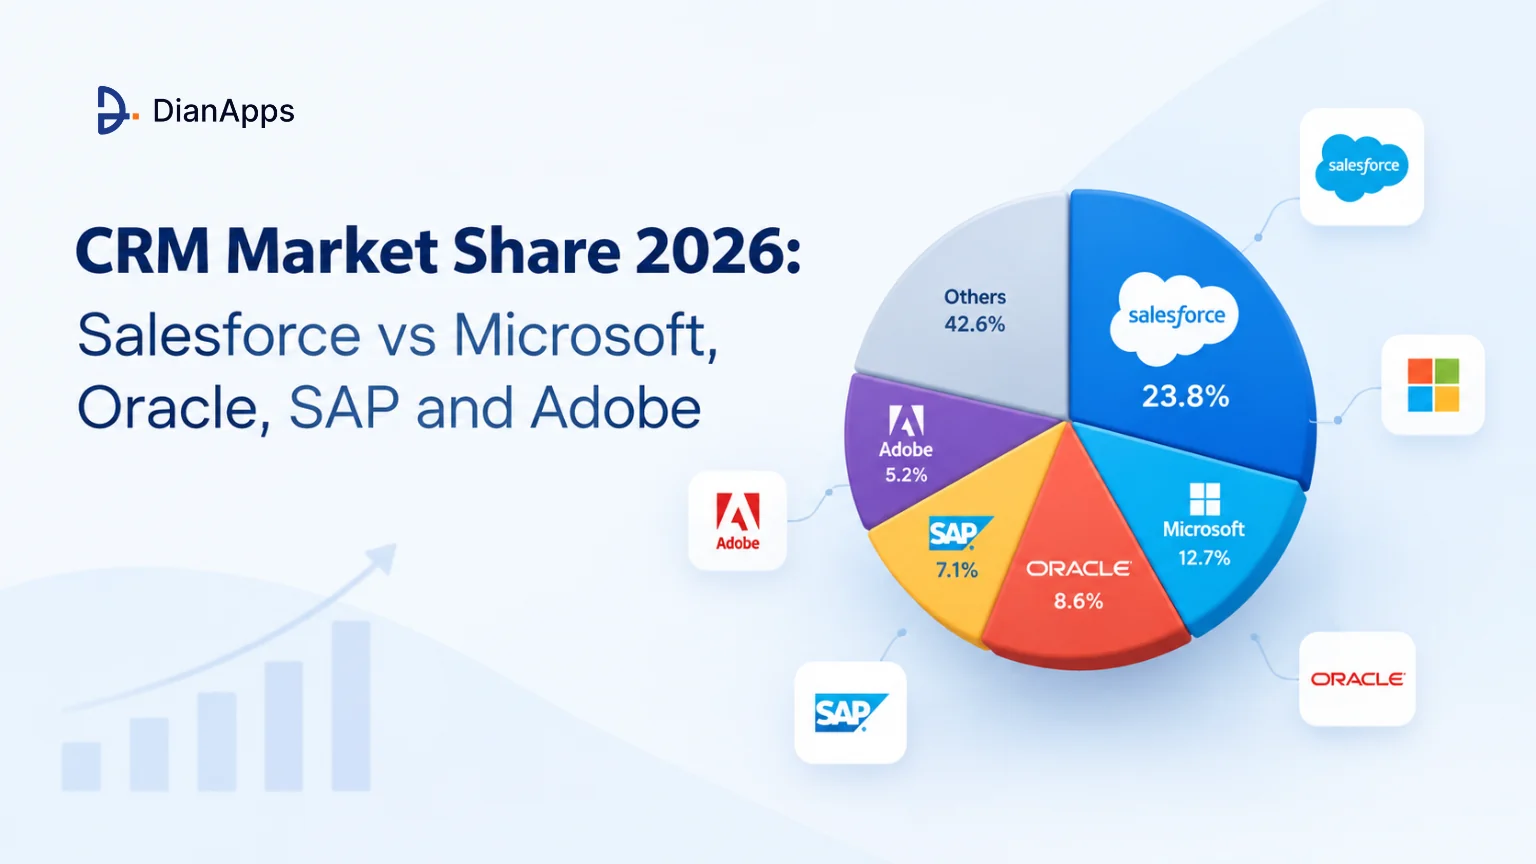
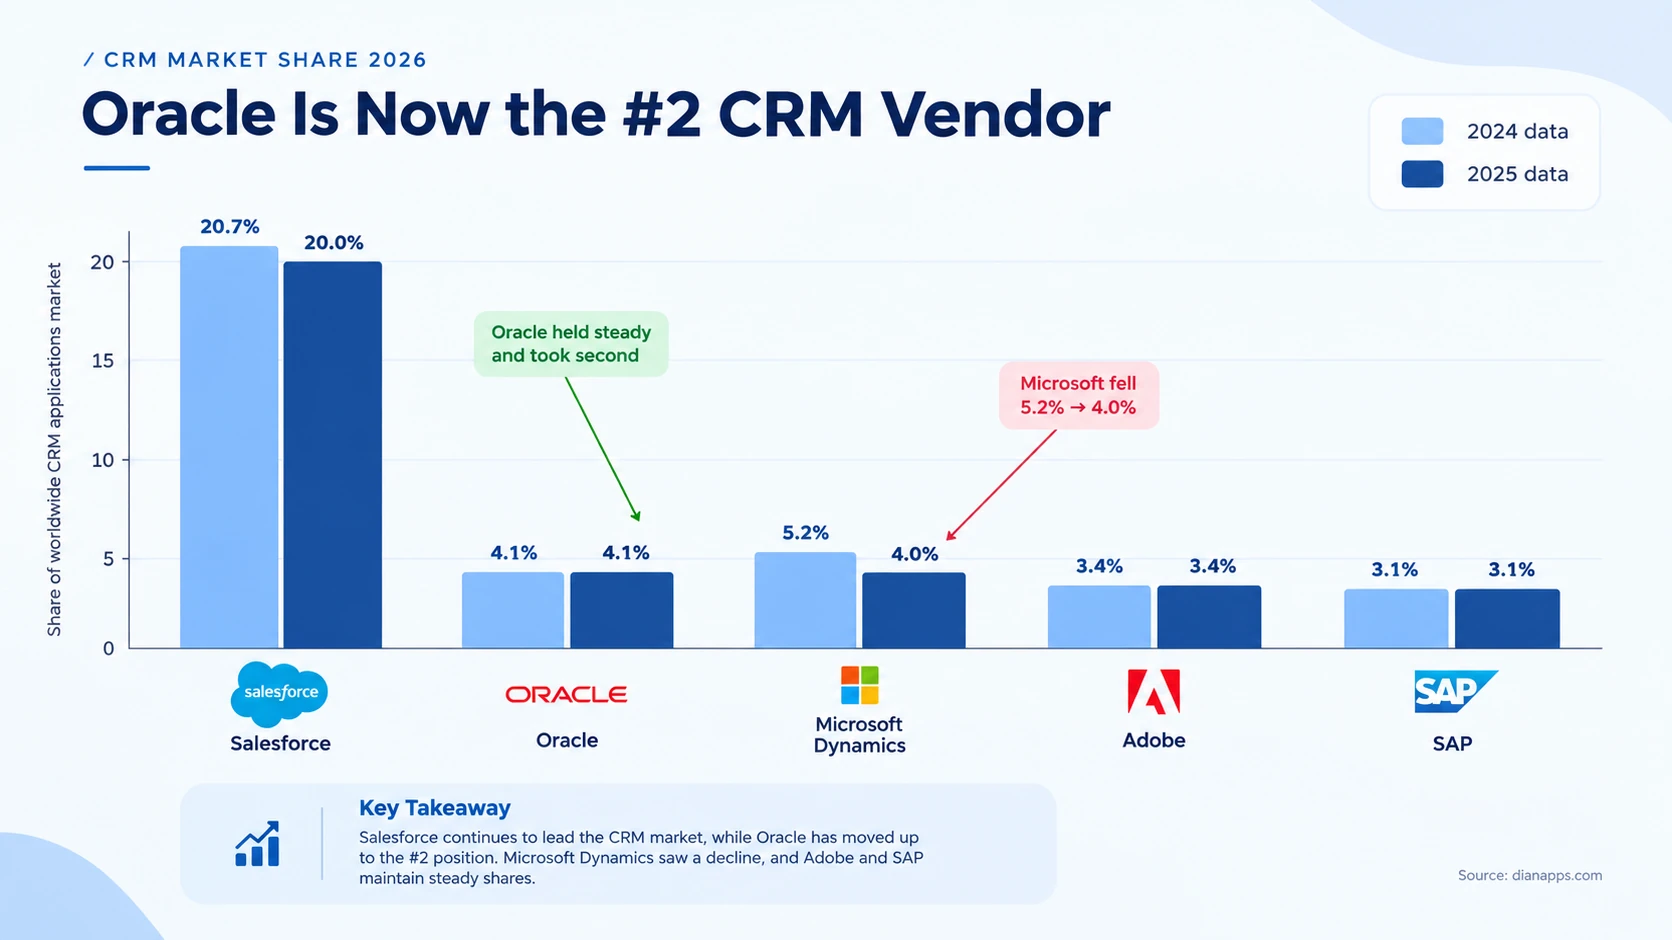
- Salesforce leads with 20.0%, followed by Oracle at 4.1% and Microsoft at 4.0%.
- Oracle overtook Microsoft for second place after Microsoft’s share fell from 5.2% to 4.0%.
- The top five vendors hold roughly 41% of the market, down from about 54% in 2007.
- Salesforce leads by revenue, while HubSpot leads by customer count, showing why different market measures tell different stories.
Quick Answer: Salesforce holds the largest CRM market share at 20.0%, while Oracle moved into second place with 4.1%, narrowly ahead of Microsoft at 4.0%. The latest data also shows the CRM market becoming more fragmented, with the top five vendors holding roughly 41% combined share.
Oracle is now the second-largest CRM vendor in the world. Microsoft held that position for years and lost it in 2025, falling from 5.2% to 4.0% while Oracle held steady at 4.1%.
Most CRM market share articles still list Microsoft second. They’re working from the previous IDC tracker edition.
The other thing most of them get wrong is the direction of travel. The top five vendors are not consolidating their grip on this market; they’ve been losing collective share to the long tail since 2007, a trend that becomes even clearer when you look at broader CRM statistics.
The Rankings
| Rank | Vendor | 2025 share | 2024 share | Direction |
|---|---|---|---|---|
| 1 | Salesforce | 20.00% | 20.70% | Down 0.7pt |
| 2 | Oracle | 4.10% | 4.10% | Flat, now second |
| 3 | Microsoft Dynamics | 4.00% | 5.20% | Down 1.2pt |
| 4 | Adobe | ~3.4% | ~3.4% | Flat |
| 5 | SAP | ~3.1% | ~3.1% | Flat |
| - | Everyone else | ~59% | - | Growing |
Source: IDC Worldwide Semiannual Software Tracker, April 2026, based on 2025 revenue. IDC does not publicly break out exact figures below the top three, so Adobe and SAP shares are approximate.
- Microsoft’s Fall Is the Story: A 1.2-point drop in a market this size is substantial, and it’s what handed Oracle second place rather than any Oracle gain.
Salesforce’s decline needs context, because it reads worse than it is. Its CRM revenue grew roughly 9.5% while the overall market grew 12.8%. For a deeper look at the company’s revenue, customers, employees, and other figures, see our Salesforce statistics guide
It lost share by growing more slowly than a fast-growing market, not by shrinking. Losing a point of share while adding close to two billion dollars of revenue is a position most vendors would accept.
What IDC Actually Counts
Worth understanding, because it explains rankings that otherwise look odd.
- IDC’s CRM Category Covers Six Functional Markets: Sales Force Productivity and Management, Marketing Campaign Management, Customer Service, Contact Centre, Advertising, and Digital Commerce Applications.
- That’s Why Adobe Is In The Top Five At All: Adobe doesn’t sell a CRM in the way a buyer would understand the term, it qualifies because marketing and commerce software is folded into the category.
- And It’s Why These Figures Won’t Match Your Shortlist: If you’re comparing Salesforce, HubSpot and Pipedrive for a sales team, IDC’s definition includes a great deal of software you’re not evaluating. Market share is useful for judging vendor stability, not for building a shortlist.
Related: Salesforce alternatives compared
Salesforce’s Full IDC Rankings
Salesforce leads more than the headline CRM category:
| Category | Position | Consecutive years |
|---|---|---|
| CRM overall | #1 | 13 |
| Sales applications | #1 | 14 |
| Customer Service | #1 | 13 |
| Marketing | #1 | 7 |
| Model-Driven Application Platforms | #1 | 11 |
| Enterprise Community | #1 | 11 |
| Integration | #1 | 4 |
| Agent Build and Deploy | #2 | New category |
The Last Row Is The Interesting One: IDC published market shares for “Agent Build and Deploy” for the first time in 2026, describing the segment as being in hypergrowth. Salesforce is second, not first, with a 17.5% share, though it grew faster than any other vendor in the category.
That’s a useful corrective to the Agentforce marketing. Salesforce is a strong player in agent platforms; it isn’t the leader there the way it is in CRM.
Related: what is Agentforce
The Market Is Fragmenting, Not Consolidating
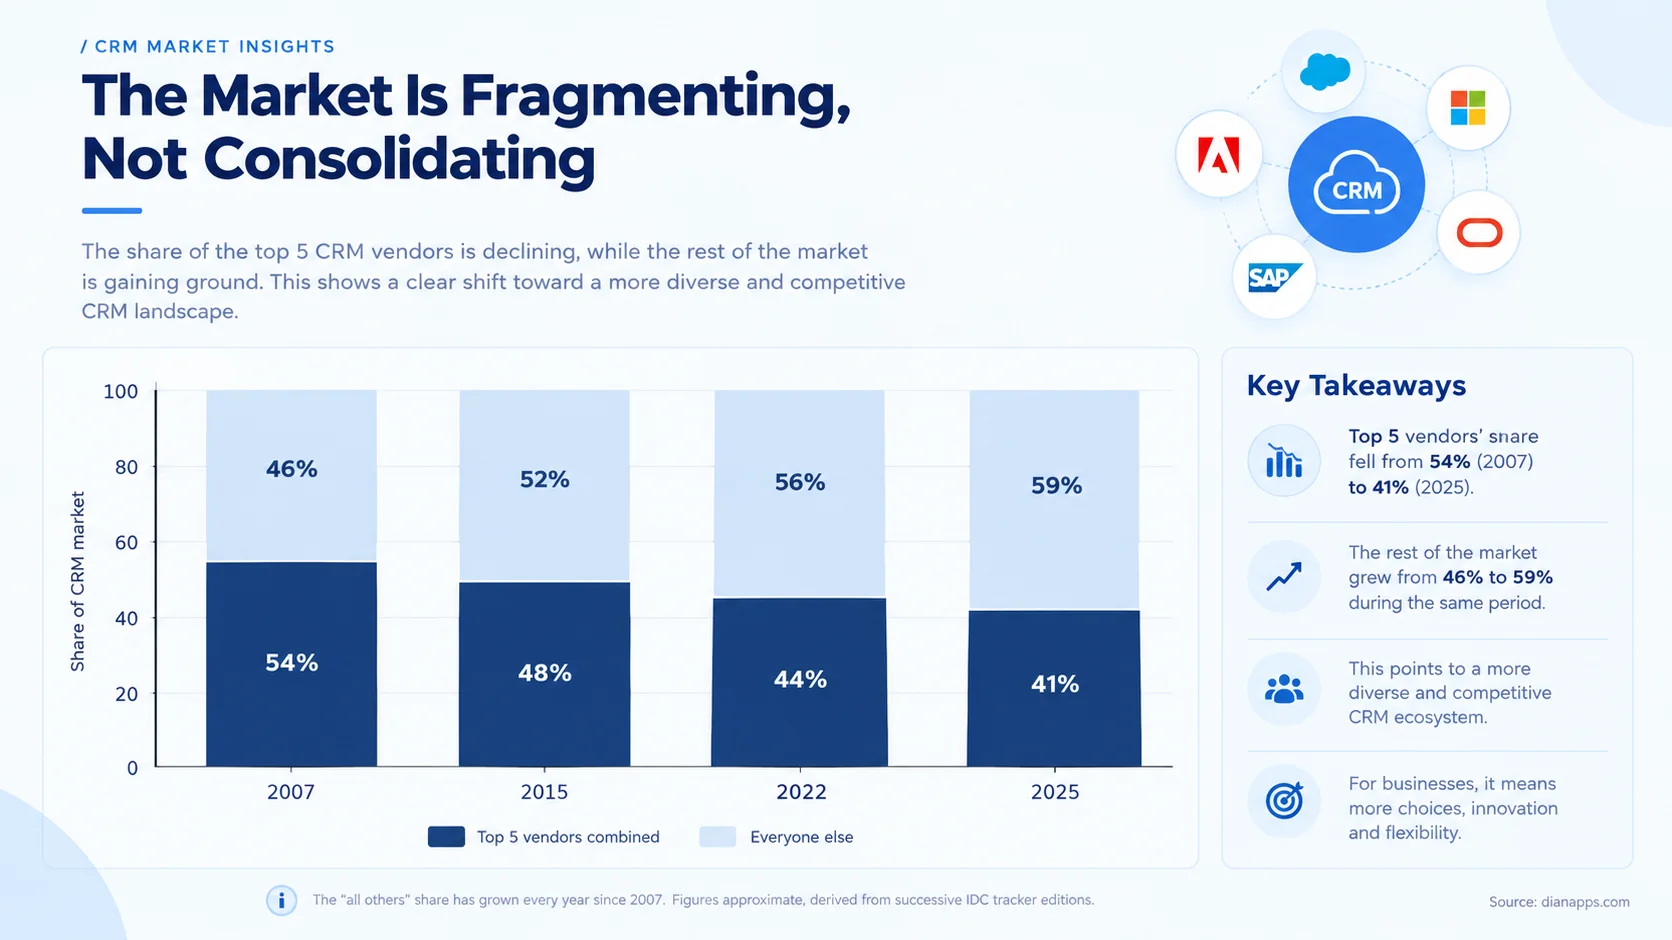
This contradicts the usual narrative, and it’s the most useful finding on this page for a buyer.
The assumption is that enterprise software consolidates, that the big vendors absorb the market. In CRM the opposite has happened consistently. The “everyone else” segment has grown from 46% in 2007 to roughly 59% today.
Why it’s happening:
- Vertical specialists win where a general CRM needs heavy customisation
- SMB-focused tools HubSpot, Pipedrive, Zoho, Freshworks took a segment the enterprise vendors served poorly
- The category keeps expanding. As IDC folds in more adjacent software, more vendors qualify
- Switching costs protect incumbents but don’t win new logos
What It Means For You: the assumption that “nobody gets fired for buying the market leader” is weaker in CRM than in most enterprise categories. A majority of the market is buying something else.
Planning a CRM Change?
Tell us what you need from your CRM, and we’ll help you plan the right approach.
Revenue Share vs Customer Count
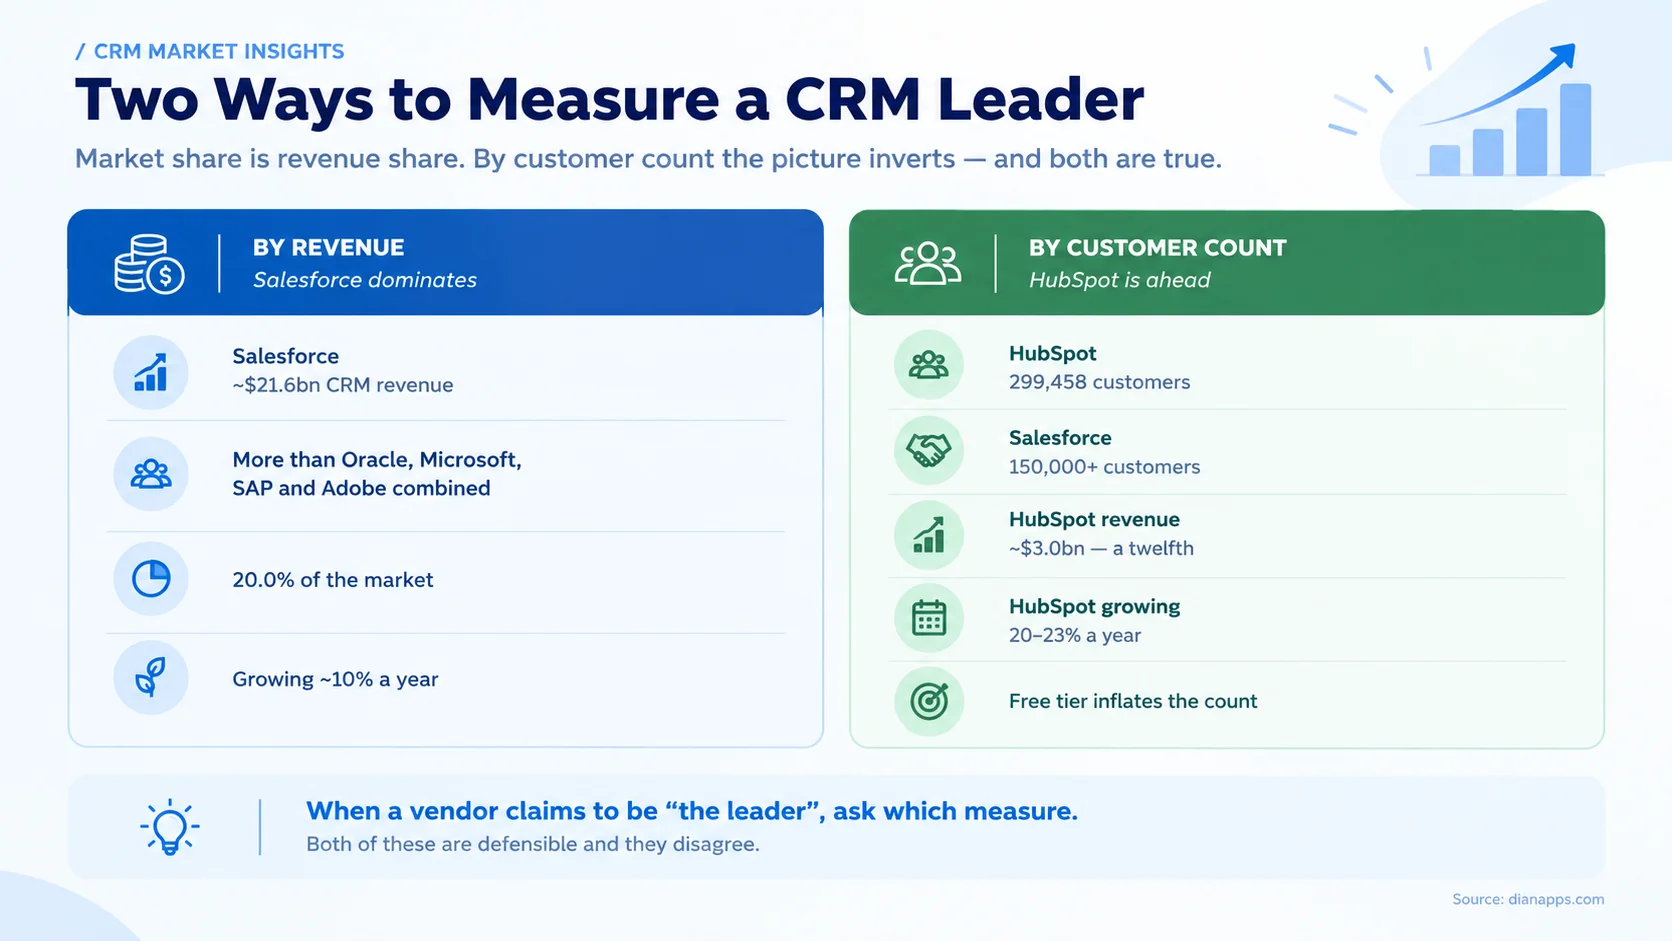
Both of these are true, and vendors pick whichever flatters them.
- By revenue, Salesforce dominates: Around $21.6 billion in CRM revenue, more than Oracle, Microsoft, SAP, and Adobe combined. That’s the basis of the 20.0% figure.
- By customer count, HubSpot is ahead: 299,458 paying customers as of Q1 2026 against Salesforce’s 150,000+, roughly double. HubSpot’s revenue is about a twelfth of Salesforce’s, which tells you the average customer is very different.
- And by growth rate, HubSpot is winning: Roughly 20–23% annually against Salesforce’s 8–11%.
- None of this makes HubSpot “bigger”: It makes it a different business serving a different segment, many small customers rather than fewer large ones, with a free tier that inflates the customer count considerably.
- The practical version: when a vendor claims to be “the leader”, ask which measure. Revenue share, customer count, install base, and growth rate produce four different winners.
Related: Salesforce vs HubSpot
Need Salesforce Developers?
Hire experienced Salesforce developers to customize, integrate, and scale your CRM.
Market Size and Growth
| Metric | Figure | Source |
|---|---|---|
| CRM category size | ~$128bn | Gartner estimate |
| Market growth rate | ~12.8% | Derived from IDC data, 2025 |
| Salesforce CRM revenue growth | ~9.5% | Derived from IDC data, 2025 |
| Salesforce total revenue | $41.5bn FY2026 | Salesforce earnings release |
| HubSpot revenue | ~$3.0bn 2025 | HubSpot earnings |
| Microsoft Dynamics 365 growth | 23% in FY25 Q4 | Microsoft earnings |
A Note on Microsoft: Its Dynamics 365 revenue is growing at 23%, yet its CRM market share fell. Those aren’t contradictory; Microsoft reports Dynamics 365 as a whole, including ERP, while IDC counts only CRM functional markets. Vendor-reported growth and analyst-measured share are different things, and vendors quote whichever is better.
Regional Picture
Salesforce claims the #1 CRM position in North America, Latin America, Western Europe, and Asia-Pacific, including Japan.
- The Honest Caveat: regional share is far less transparent than global. IDC doesn’t publish detailed regional breakdowns publicly, so most regional claims come from vendors citing IDC selectively.
- What’s Observable: the long tail is stronger in some regions than others. Zoho has a disproportionate share in India, local vendors matter more in Japan and Germany than global figures suggest, and SMB tools have taken more of the European market than of the US one.
If regional presence matters to your decision, weigh local partner availability and language support more heavily than global share figures. For companies evaluating Salesforce across different markets, Salesforce consulting services can also help align the platform with regional workflows, integrations, and business requirements.
Related: Salesforce partners in India
What This Means If You’re Buying
Three things the numbers genuinely tell you, and two they don’t.
- They Tell You About Vendor Stability: Salesforce at 20% with 13 years at #1 is not going anywhere. That answers a legitimate board-level question.
- They Tell You About Ecosystem Depth: Market share drives partner availability, hiring pools, third-party apps and community support. A larger vendor means it’s easier to find people who know the product, which is a real operational advantage.
- They Tell You The Market Is More Open Than It Looks: Fifty-nine percent of it isn’t the big five.
- They Don’t Tell You About Fit: The best-fitting CRM for a 30-person business is rarely the market leader, and IDC’s category definition includes software you’d never evaluate. This is where Salesforce consulting services can help businesses assess their workflows, integration needs, and long-term requirements before committing to a platform.
- And They Don’t Tell You About Cost: Market share says nothing about what you’ll pay or what implementation will cost. See Salesforce pricing and Salesforce vs custom CRM.
Need Salesforce Guidance?
Get expert Salesforce guidance for implementation, customization, and long-term CRM growth.
Where to Go Next
For Salesforce’s own numbers in detail, Salesforce statistics 2026.
For the alternatives that make up the long tail, Salesforce alternatives compared, vs HubSpot, vs Zoho, and vs Microsoft Dynamics.
For whether to buy at all, Salesforce vs custom CRM and signs you’ve outgrown your CRM.
For cost rather than share, Salesforce pricing and editions compared.
For the platform itself, what is Salesforce and Salesforce clouds compared.
For the wider data picture, CRM statistics.
The Market Leader Isn’t Automatically Your Answer
Fifty-nine percent of the CRM market is buying something other than the big five vendors. That number should carry more weight in a shortlist than it usually does.
Salesforce is the right answer for a great many organisations and genuinely the wrong one for others, and the deciding factor is process complexity, not vendor ranking.
 0 comments





Leave a Comment
Your email address will not be published. Required fields are marked *